Why the Renters' Rights Act Is Pushing Investors from Buy-to-Let to Serviced Accommodation
For landlords already navigating higher borrowing costs, tax changes and tighter compliance requirements, the Renters’ Rights Act represents another material adjustment to the traditional buy-to-let model.
The legislation is not the end of private renting, despite some of the more dramatic headlines. However, it does reduce landlords’ control over tenancy duration, possession and rent-setting. As a result, investors are reassessing whether the standard residential tenancy remains the most suitable structure for every property in their portfolio.
Lenders and market analysts are now discussing a potential shift towards alternative operating models, including serviced accommodation, short-stay rentals and the aparthotel model. These strategies are not risk-free, nor are they suitable for every property. Nevertheless, they can provide experienced investors with greater operational flexibility and a more diversified income profile.
What the Renters’ Rights Act changes for landlords
The Renters’ Rights Act 2025 received Royal Assent on 27 October 2025, with the principal tenancy reforms taking effect in England on 1 May 2026.
The Government’s official guide to the Renters’ Rights Act confirms several important changes for private landlords.
Section 21 has been abolished
The most prominent change is the abolition of Section 21 “no-fault” evictions.
Previously, a landlord could generally recover possession at the end of a tenancy without proving tenant fault, provided the correct notice and procedures had been followed. Under the new framework, landlords must instead rely on a prescribed Section 8 ground for possession.
These grounds include:
Rent arrears
Antisocial behaviour
Serious breaches of the tenancy
The landlord wishing to sell
The landlord or a close family member wishing to move into the property
Although the Act preserves legitimate routes for landlords to regain possession, the process is now more evidence-led. Sale and occupation grounds also carry longer notice periods, and they cannot generally be used during the first 12 months of a new tenancy.
For an investor seeking to sell, refinance or reposition an asset, this can materially affect timing. The property may remain occupied when a vacant possession sale would otherwise have been preferred.
Fixed-term tenancies are replaced by periodic tenancies
Assured Shorthold Tenancies are being replaced by assured periodic tenancies. In practical terms, most private tenancies will operate on a rolling basis rather than ending on a predetermined date.
A tenant can remain in the property until they decide to leave, provided they continue to comply with the tenancy. They will generally be able to give two months’ notice, aligned with the rent period.
This creates a more flexible system for tenants. For landlords, however, it introduces less certainty around the length of each letting period. An investor cannot assume that a six- or twelve-month agreement will provide a fixed period of income or a predictable opportunity to review the property.
Rent increases must follow a formal process
The legislation does not introduce conventional rent controls. Landlords can still increase rent to reflect the market rate.
However, rent increases in the private rented sector must generally take place once per year through the Section 13 process, with at least two months’ notice. Tenants can challenge an increase at the First-tier Tribunal if they believe it exceeds the market rent.
This does not prevent sustainable rental growth, particularly in areas with a structural shortage of good-quality housing. Nevertheless, it limits the speed and flexibility with which landlords can respond to changing costs, mortgage rates and local demand.
The Act also prohibits rental bidding and restricts landlords from requiring large amounts of rent in advance for new tenancies.
Compliance and administration are increasing
The Act also introduces a Private Rented Sector Landlord Ombudsman and a Private Rented Sector Database. Further measures relating to property standards, including the Decent Homes Standard and Awaab’s Law, are expected to add to landlords’ obligations.
Responsible landlords already maintain safety certificates, repair records and clear management procedures. The issue is not whether professional standards are appropriate; they are. The issue is that administration, compliance and enforcement costs can reduce net yields, particularly for highly leveraged landlords with limited operating margins.
Why lenders are reassessing traditional buy-to-let
The market is not experiencing a uniform withdrawal from buy-to-let. Well-capitalised landlords with conservative borrowing and professional systems remain active.
However, the economic disparity between different types of investor is becoming more pronounced.
Morningstar DBRS has warned that landlords unwilling or unable to adapt to the new regulatory and financial environment may leave the private rented sector. As reported by Mortgage Solutions, buy-to-let mortgage advances were around 40% lower in 2025 than in 2022, with regulatory changes and persistent cost pressures continuing to restrict growth.
Research from Cushman & Wakefield similarly suggests that the reforms could increase operating costs, create uncertainty over tenancy duration and influence property valuations. Its analysis identified short-term lettings as one possible destination for landlords seeking higher returns with fewer of the restrictions associated with regulated private tenancies.
The long-term implication is likely to be professionalisation rather than collapse. Smaller landlords may sell, while larger operators with stronger balance sheets and more sophisticated management will absorb the additional requirements.
For investors, this raises a practical question: should every residential asset continue to be operated as a conventional buy-to-let?
Serviced accommodation offers a different operating structure
Serviced accommodation is not simply buy-to-let with more frequent bookings. It is an operating business built around guest stays, corporate accommodation, relocation demand and leisure travel.
Occupants generally stay under booking terms or licences rather than assured residential tenancies. Consequently, the Renters’ Rights Act does not apply in the same way to genuine short-stay guest accommodation.
This can give the owner or operator greater control over:
Length and timing of stays
Pricing and seasonal adjustments
Property availability
Maintenance windows
Furnishing and presentation
The balance between corporate, relocation and leisure demand
That flexibility is particularly relevant when costs are changing quickly. Instead of waiting for an annual rent review, an operator can adjust nightly or weekly rates in response to demand, subject to local regulation, planning requirements and market conditions.
The model can also diversify demand. A well-positioned serviced apartment may appeal to corporate travellers, relocation agents, contractors, visiting professionals, families and tourists. This is materially different from relying on a single household and a single monthly rent.
The aparthotel model: more control, but more responsibility
The aparthotel model is an increasingly relevant option for investors seeking a structured alternative to traditional buy-to-let.
A typical aparthotel combines the features of a private apartment with the operational framework of hospitality. Guests benefit from a kitchen, living space and greater independence than a conventional hotel room, while the operator manages bookings, cleaning, guest communication and maintenance.
For owners, the model can offer:
A diversified revenue profile
Income may come from several booking channels and customer segments rather than one long-term tenancy.Dynamic pricing potential
Rates can respond to business events, tourism, seasonality and local supply and demand.Greater asset control
The owner can schedule maintenance, refurbishment and inspections between stays.A professional management structure
A specialist operator can manage marketing, guest services, housekeeping and compliance.Potentially stronger alignment with commercial use
Some aparthotel schemes operate under commercial or hospitality use classifications. However, classification must always be verified at asset level. C1 use is not an automatic exemption from every regulation, and planning, licensing, lease, insurance and lender requirements remain essential considerations.
The regulatory escape hatch is not a shortcut
It is tempting to describe serviced accommodation as a regulatory escape hatch. In a limited sense, it can provide distance from the specific tenancy rules affecting assured residential lets.
However, investors should not confuse a different regulatory framework with an absence of regulation.
A compliant serviced accommodation strategy may require consideration of:
Planning permission and permitted use
Local authority restrictions
Lease and freeholder consent
Specialist insurance
Gas and electrical safety
Fire risk management
Licensing requirements
National short-term-let registration proposals
Mortgage or commercial finance conditions
Business rates and tax treatment
Data protection and guest management
Operational performance also depends on occupancy, average daily rate, cleaning costs, utilities, maintenance and distribution fees. A serviced apartment can generate higher gross income than a standard buy-to-let, but the net result depends on disciplined management.
This is why professional oversight matters. Guestz’s landlord service covers valuation and checks, professional photography, marketing, bookings, guest communication, cleaning, deposits and emergency management. For an investor, the objective is not merely to achieve a higher headline yield; it is to create a resilient, compliant and well-managed income stream.
Should investors abandon buy-to-let?
No. A rational property strategy should not be dictated by one piece of legislation or one year of market volatility.
Traditional buy-to-let remains appropriate where the property benefits from strong long-term tenant demand, stable financing, manageable compliance costs and a location with durable employment or population growth. The model also offers a relatively straightforward operating structure for investors prioritising long-term capital preservation and predictable occupancy.
Serviced accommodation may be more appropriate where the property is:
In a strong business or tourism location
Suitable for professional short stays
Subject to appropriate planning and lease arrangements
Capable of delivering a hospitality-standard guest experience
Supported by an experienced management operator
Some investors may choose to maintain both strategies. A diversified portfolio could include conventional buy-to-let assets for stability and serviced apartments for income flexibility, provided each property is assessed on its own fundamentals.
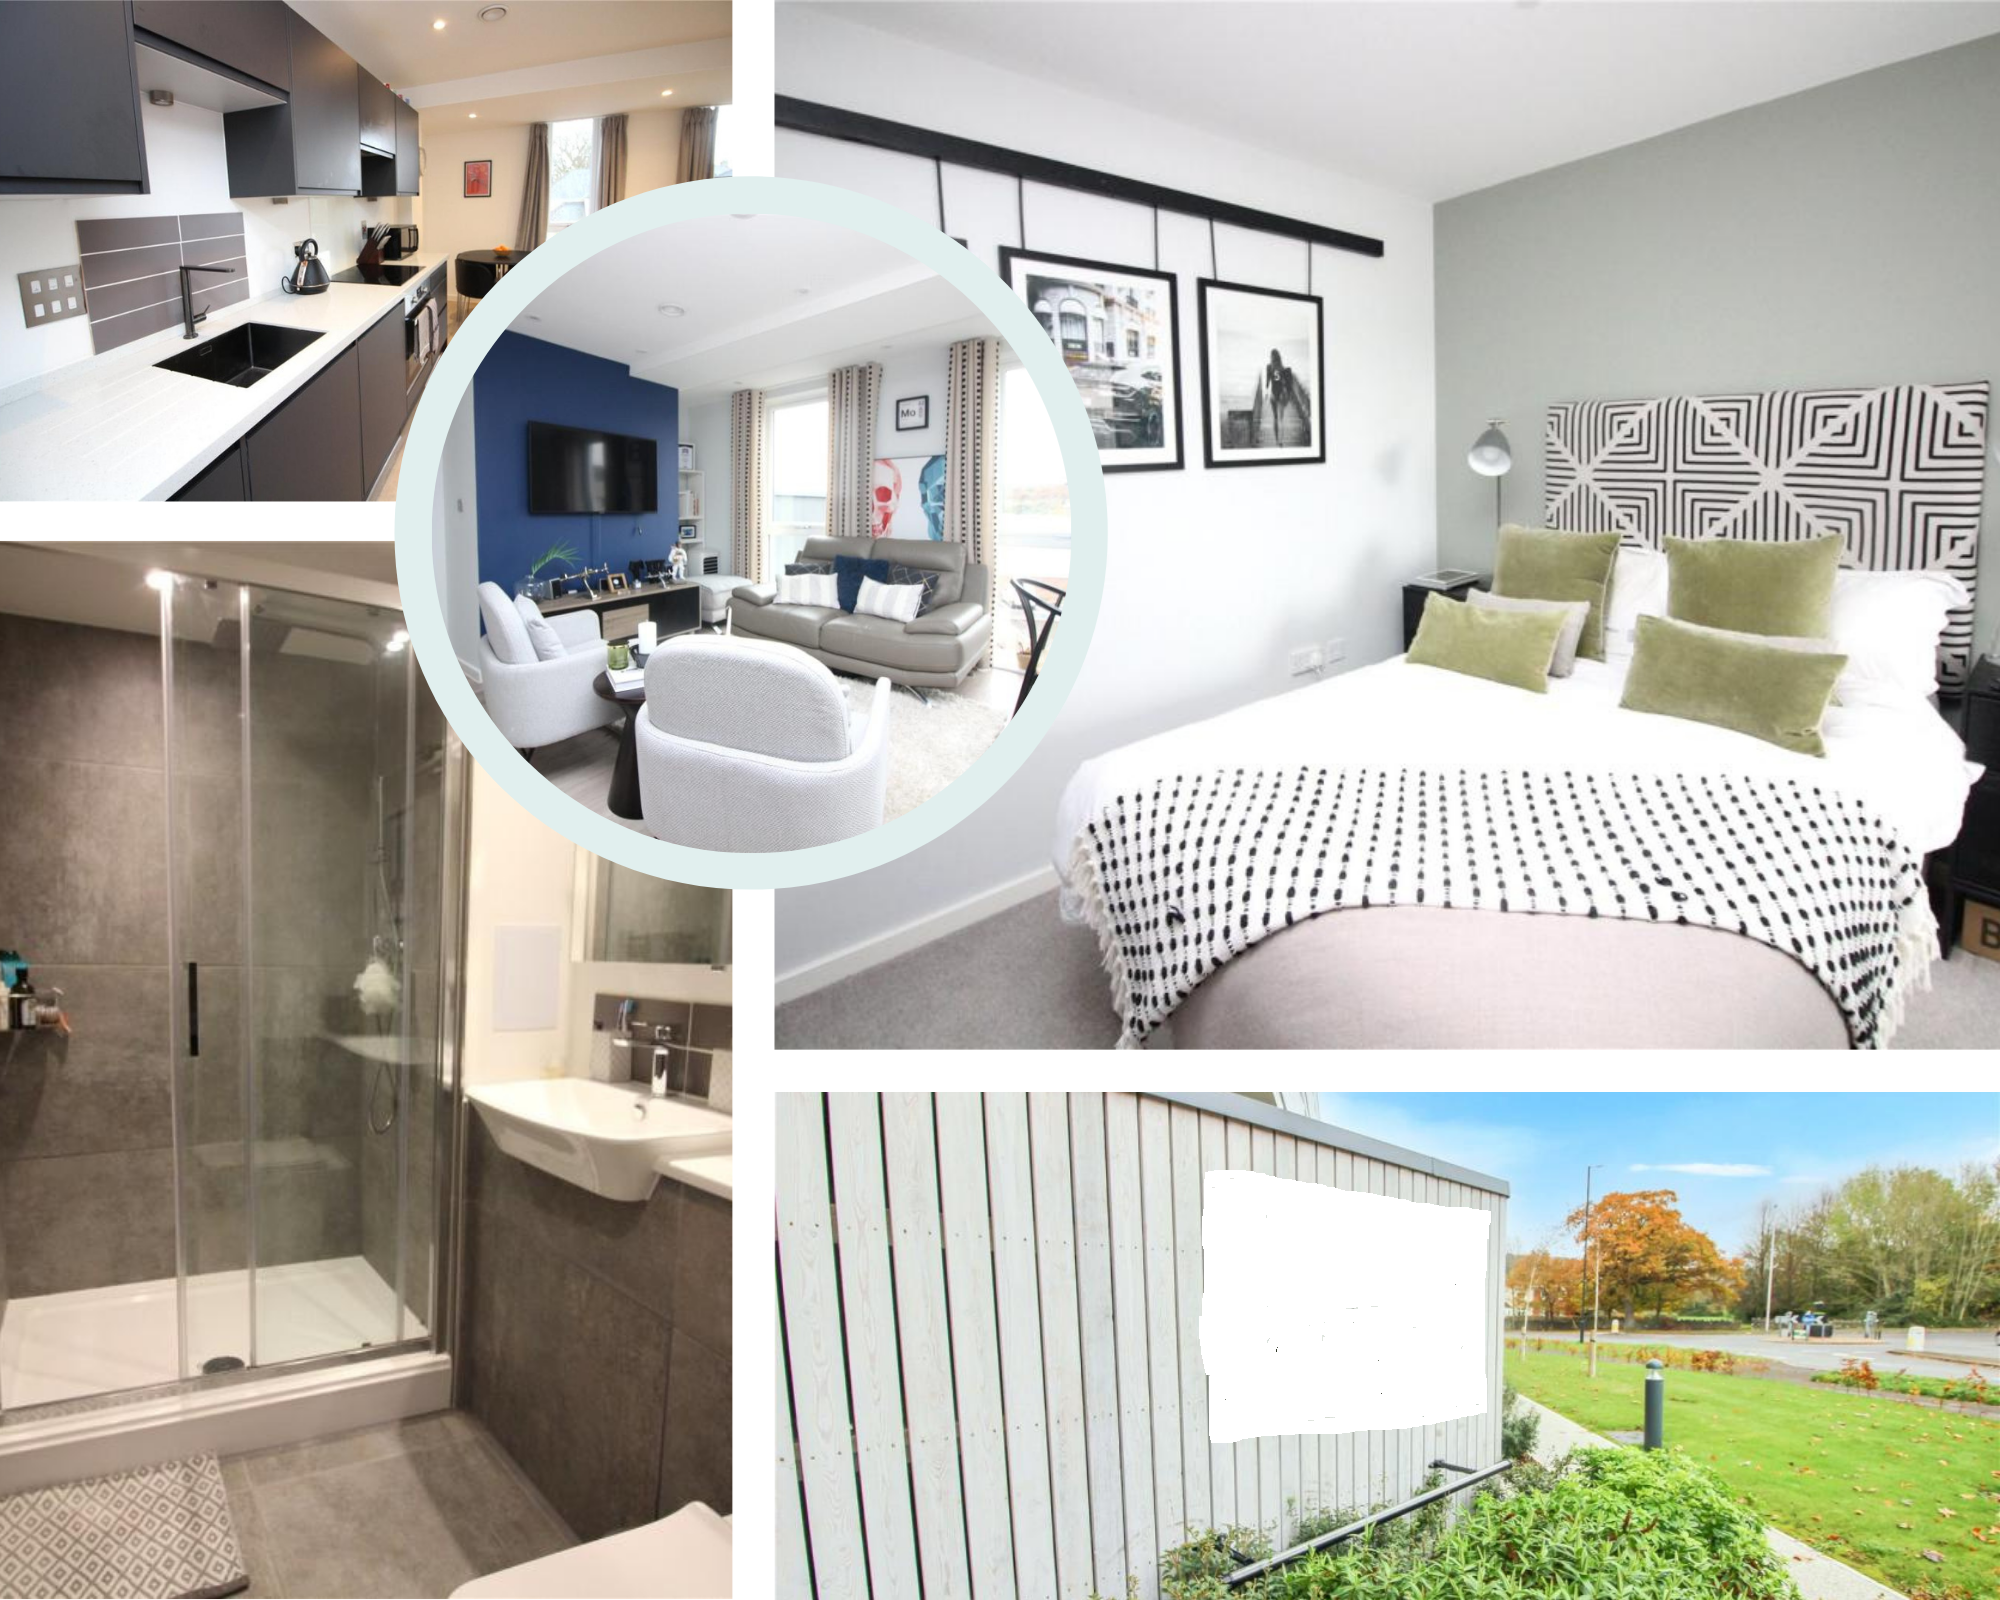
For example, Coates House in Nailsea provides contemporary apartments within reach of Bristol, offering a useful illustration of how location, accommodation quality and regional demand can combine within a serviced model.
The long-term outlook: professionalisation, not panic
The Renters’ Rights Act creates genuine challenges for landlords. Section 21 has gone, periodic tenancies reduce certainty over occupancy, rent increases follow a more formal process and compliance obligations are expanding.
Nevertheless, these pressures are more likely to accelerate the professionalisation of property investment than undermine the underlying market.
The UK continues to experience substantial demand for quality accommodation. The investors most likely to perform well will be those who understand the distinction between gross and net yield, assess regulation before acquisition and select an operating model that suits the asset.
For some properties, that will remain buy-to-let. For others, serviced accommodation or an aparthotel-style strategy may offer greater control, more diversified demand and a more responsive income structure.
The essential point is to avoid both complacency and sensationalism. The market is undergoing a readjustment. With careful due diligence, appropriate finance and professional management, the underlying strengths of UK property investment remain robust.
If you are reviewing your portfolio or considering a move from buy-to-let into serviced accommodation, contact Residential Estates to discuss your objectives and available investment options. This article is for general information only and does not constitute legal, tax or financial advice.