Why More Investors Are Buying Property Through a Limited Company: The Benefits Explained
The structure used to own a buy-to-let property can have a meaningful effect on taxation, finance, administration and long-term portfolio planning. It is therefore unsurprising that more professional landlords are considering a limited company rather than treating each property as an isolated personal investment.
Recent data highlighted in our previous article shows that 45.1% of UK buy-to-let property is now company-owned, rising to 57.6% among landlords with 20 or more properties. The figures do not mean that incorporation is automatically appropriate for every investor. They do, however, demonstrate a broader shift: property investment is becoming more structured, more commercially managed and increasingly aligned with the way other businesses operate.
For the experienced investor, the question is not whether a limited company is fashionable. It is whether a company structure supports the intended investment strategy, cash-flow requirements and long-term objectives.
> Important: This article is for general information only. Residential Estates is not FCA approved and cannot provide tax advice or financial advice. We work in partnership with Zeal, specialist property tax accountants, who can provide guidance based on your circumstances.
1. Corporation tax can be lower than higher-rate income tax
One of the principal attractions of a limited company buy-to-let structure is the rate at which rental profits may be taxed.
For the current corporation tax regime, company profits are generally subject to:
A 19% small profits rate for profits of £50,000 or less
A main rate of 25% for profits above £250,000
Marginal relief for profits between those thresholds
The thresholds can be affected by accounting periods and associated companies, so they should not be viewed as a simple allowance available separately to every company.
Nevertheless, these rates can compare favourably with personal income tax rates of up to 45% for additional-rate taxpayers. That disparity is particularly relevant where an investor already has substantial employment, pension or business income and rental profits would otherwise sit on top of their existing earnings.
The benefit is not simply that a company always pays less tax. The more nuanced point is that profits retained within a company may initially be taxed at corporation tax rates rather than being immediately exposed to higher personal income tax.
This can improve the amount available for reinvestment, subject to the wider costs of operating the company and the eventual tax position when funds are extracted.
For further context, investors can review the official GOV.UK guidance on corporation tax rates.
2. Mortgage interest can be deducted in full
For many highly mortgaged landlords, the treatment of finance costs is one of the most significant benefits of company ownership.
Since the introduction of the Section 24 finance cost restriction, individual landlords generally cannot deduct all residential mortgage interest from rental income when calculating taxable profit. Instead, they receive tax relief at the basic rate on qualifying finance costs.
This means an individual landlord can, in some circumstances, be taxed on a rental profit figure that does not reflect the full cash cost of mortgage interest.
A UK resident company is not subject to this specific restriction. Mortgage interest and other qualifying finance costs can generally be deducted when calculating the company’s taxable profit, provided the borrowing and expenditure meet the relevant rules.
For example, a company receiving £40,000 of rental income and paying £10,000 in mortgage interest would generally calculate its taxable profit after taking that interest into account, alongside other allowable business costs.
That distinction can be material for a higher-rate taxpayer, particularly where:
The property is substantially mortgaged
Interest rates are relatively high
The investor plans to retain profits
The portfolio is expected to grow over time
The wider point is that a limited company can produce a clearer relationship between rental income, operating expenses, finance costs and taxable profit. However, the figures must be modelled carefully rather than assumed.
HMRC provides further information on finance cost restrictions for residential landlords.
3. Greater flexibility when extracting profits
A company structure can also offer flexibility in deciding when and how profits are taken.
Depending on the circumstances, an owner may consider a combination of:
Dividends
A salary
Pension contributions
Retained profits
Reinvestment in further property
Repayment of properly documented director’s loans
The appropriate combination depends on the company’s accounts, the shareholder’s personal income, available allowances and wider objectives. It is not a question of selecting one method in isolation.
The most important benefit for many portfolio landlords is timing flexibility. Instead of automatically withdrawing every pound of profit in the year it is generated, the company may retain some funds for:
Deposits on future purchases
Refurbishment and compliance works
Mortgage reduction
Professional fees
Cash-flow reserves
Acquiring additional properties
This can be particularly useful for an investor seeking to build a portfolio rather than rely on one property as an immediate personal income stream.
There is, however, an important caveat. Corporation tax is not necessarily the final tax cost. Dividends may be taxable when received personally, and the company’s profits may therefore face a further layer of taxation if they are extracted. The company route tends to be most compelling where the investor can retain and redeploy at least part of the profits.
4. Capital gains can create additional planning options
When a company sells a property, it does not pay Capital Gains Tax in the same way as an individual. Instead, the chargeable gain is generally added to the company’s taxable profits and subject to corporation tax.
This can be helpful where sale proceeds remain inside the company and are used to acquire another investment. The investor may be able to delay personal taxation until money is extracted, allowing more capital to remain available within the business.
A company structure can also create different planning options because the owner holds shares in the company rather than directly owning each property. In some circumstances, an investor may consider:
Transferring shares rather than individual property titles
Bringing in a business partner through a share issue
Selling part of a company
Retaining proceeds for future acquisitions
Structuring ownership around longer-term succession objectives
This should not be mistaken for a guaranteed tax advantage. A company does not benefit from an individual’s Capital Gains Tax annual exempt amount, and gains may be taxed at corporation tax rates. If the sale proceeds are then distributed to shareholders, a further personal tax charge may arise.
The correct conclusion is therefore measured: corporate ownership may offer additional planning flexibility, but the tax outcome depends on the property, the company, the shareholder and the eventual exit route.
5. Share ownership can support succession planning
Property held personally can be difficult to divide, transfer or manage across multiple beneficiaries. Shares in a property company can offer a more structured mechanism for ownership and succession planning.
For example, a company may be able to use:
Different classes of shares
Voting and non-voting shares
Share transfers over time
Arrangements allocating future growth
Formal shareholder agreements
A clearer division between control and economic interest
A founder may, subject to professional advice, retain control over existing value while allocating future growth to other family members or investors. This can be more administratively straightforward than repeatedly transferring interests in individual properties.
However, company shares remain assets of the shareholder and may form part of their estate for inheritance tax purposes. Business Property Relief and other inheritance tax provisions are complex and do not automatically apply to every property investment company.
Succession planning should therefore begin well before a transfer is required. It should also be reviewed alongside wills, shareholder agreements, valuations and the investor’s wider estate.
6. A company structure can support professionalisation and scale
Tax is only one part of the decision. A limited company can also provide a more commercial framework for operating a portfolio.
A company may make it easier to:
Separate property income and expenditure from personal finances
Add shareholders or investment partners
Define responsibilities through formal agreements
Maintain consistent records across multiple properties
Present a professional structure to lenders and service providers
Build systems suitable for long-term expansion
This is one reason company ownership has become more prevalent among larger landlords. A portfolio of 20 properties requires a different operating discipline from a single rental house. Banking, bookkeeping, compliance, tenant management, maintenance and reporting all become more important as the number of assets increases.
A professional structure does not eliminate risk. Nor does it guarantee better returns. It can, however, support the institutional-style operation required to manage a growing buy-to-let business responsibly.
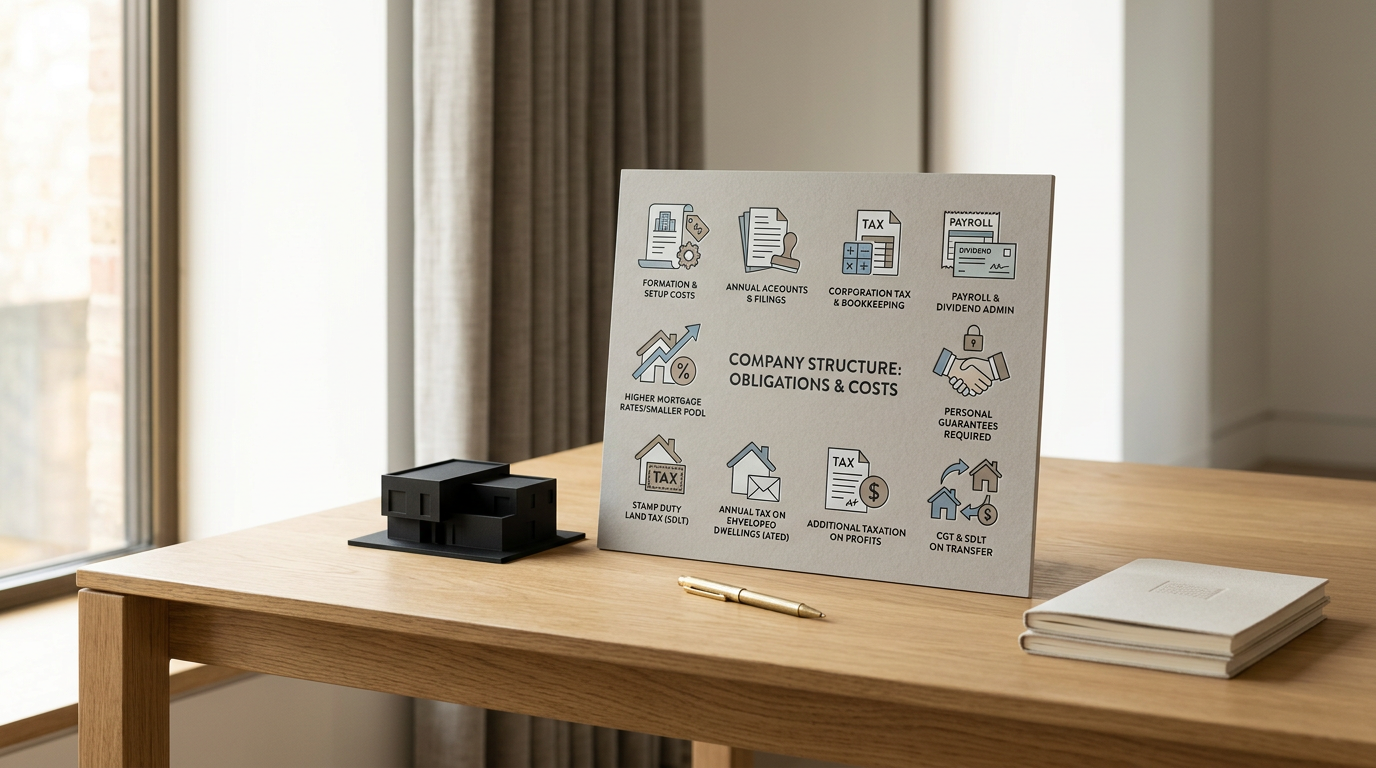
The costs and limitations should not be overlooked
The benefits of a limited company buy-to-let structure must be assessed alongside its obligations.
Potential disadvantages include:
Company formation and professional setup costs
Annual accounts and Companies House filings
Corporation tax returns and bookkeeping
Payroll or dividend administration
Potentially higher mortgage rates or a smaller lender pool
Personal guarantees required by some lenders
Stamp Duty Land Tax implications
Possible Annual Tax on Enveloped Dwellings obligations for higher-value dwellings
Additional taxation when profits are extracted
Potential Capital Gains Tax and SDLT consequences when transferring personally owned property into a company
The treatment of SDLT is especially important where an investor is considering moving an existing property into a company. Incorporation should not be assumed to be a simple administrative change; it can be treated as a disposal or acquisition for tax purposes, depending on the circumstances.
This is why a company should normally be established before purchasing, rather than treated as an afterthought. A specialist adviser can assess the proposed ownership structure, borrowing, shareholdings, acquisition costs and exit strategy before a transaction takes place.
How Residential Estates supports the wider property cycle
As the UK buy-to-let market professionalises, investors of every size are becoming more deliberate about ownership, financing and management.
Residential Estates supports clients across the full property cycle: Invest, Buy, Rent and Stay. This includes sourcing and supporting UK property investment opportunities, residential sales and lettings, long-term property management and serviced accommodation through Guestz.
For investors using a company structure, professional management can help maintain accurate operational records, protect rental performance and reduce the day-to-day burden associated with a growing portfolio. Our property management service supports both long-term and short-term rental strategies, while our property investment service helps investors assess opportunities in the context of their wider objectives.
We also work in partnership with Zeal, specialist property tax accountants, so investors can seek appropriate guidance on company structure, finance costs, capital allowances, profit extraction and portfolio planning.
A structure for the strategy, not a strategy in itself
The increasing use of limited companies reflects a broader change in UK property investment. Landlords are operating more professionally, considering long-term growth and treating property as a business rather than a collection of disconnected assets.
The underlying benefits can be substantial:
Corporation tax rates may compare favourably with higher-rate income tax
Finance costs can generally be deducted within the company
Profits can be retained and reinvested
Share ownership may provide succession and partnership flexibility
A company can support clearer administration as a portfolio grows
Nevertheless, incorporation is not automatically the correct answer. The most sustainable structure is the one that reflects the investor’s financing, tax position, cash-flow needs, family objectives and intended exit route.
*Residential Estates is not FCA approved and cannot provide tax or financial advice. This article is general information and does not constitute a personal recommendation. Tax rules, rates and reliefs can change, and individual outcomes depend on the facts of each case. Residential Estates maintains a partnership with Zeal, specialist property tax accountants, but investors should obtain appropriate independent professional advice before acting.
If you are considering a limited company buy-to-let purchase, speak with a Residential Estates Investment Consultant about the property and management strategy. For tax structuring, seek specialist guidance from Zeal or your own qualified adviser before committing to a purchase or transferring an existing property.